
Balancing Net-30 vs. Net-60 Payment Cycles: Cash Flow Engineering for App and Web Publishers
When an OpenRTB 2.6 auction clears on a client device or a Server-Side Ad Insertion (SSAI) stitcher, the winning Demand-Side Platform (DSP) fires a billing
When an OpenRTB 2.6 auction clears on a client device or a Server-Side Ad Insertion (SSAI) stitcher, the winning Demand-Side Platform (DSP) fires a billing notice URL (burl) or a VAST 4.3 <Impression> tracking pixel within 50 to 250 milliseconds. Yet the fiat currency backing that cleared impression takes anywhere from 30 to 90 days to settle into the publisher's operating bank account. For digital publishers scaling across Mobile App, Connected TV (CTV), and high-volume Web properties, this latency between real-time protocol execution and physical clearinghouse settlement is one of the primary operational bottlenecks in programmatic monetization.
AdOps architects traditionally optimize header bidding wrappers and server-side auctions purely for gross effective cost per mille (eCPM) and fill rate. However, treating a $5.00 CPM bid settling on Net-30 terms as mathematically equivalent to a $5.05 CPM bid settling on Net-60 or Net-90 terms ignores the time value of money, working capital velocity, and upstream counterparty credit risk. When a publisher scales paid User Acquisition (UA) or absorbs heavy cloud infrastructure and CDN egress fees, extending Days Sales Outstanding (DSO) by an additional 30 days can stall growth even when unit economics appear profitable on a real-time dashboard.
Engineering a resilient monetization stack requires aligning auction mechanics with treasury management. By analyzing how funds flow from advertisers through agencies, DSPs, and Supply-Side Platforms (SSPs), technical leaders can configure auction tiering, bid shading adjustments, and demand partner allocations that balance top-line yield against predictable Net-30 and Net-60 liquidity.
The Clearinghouse Timeline: Why DSP-to-SSP Settlement Takes 45 to 90 Days
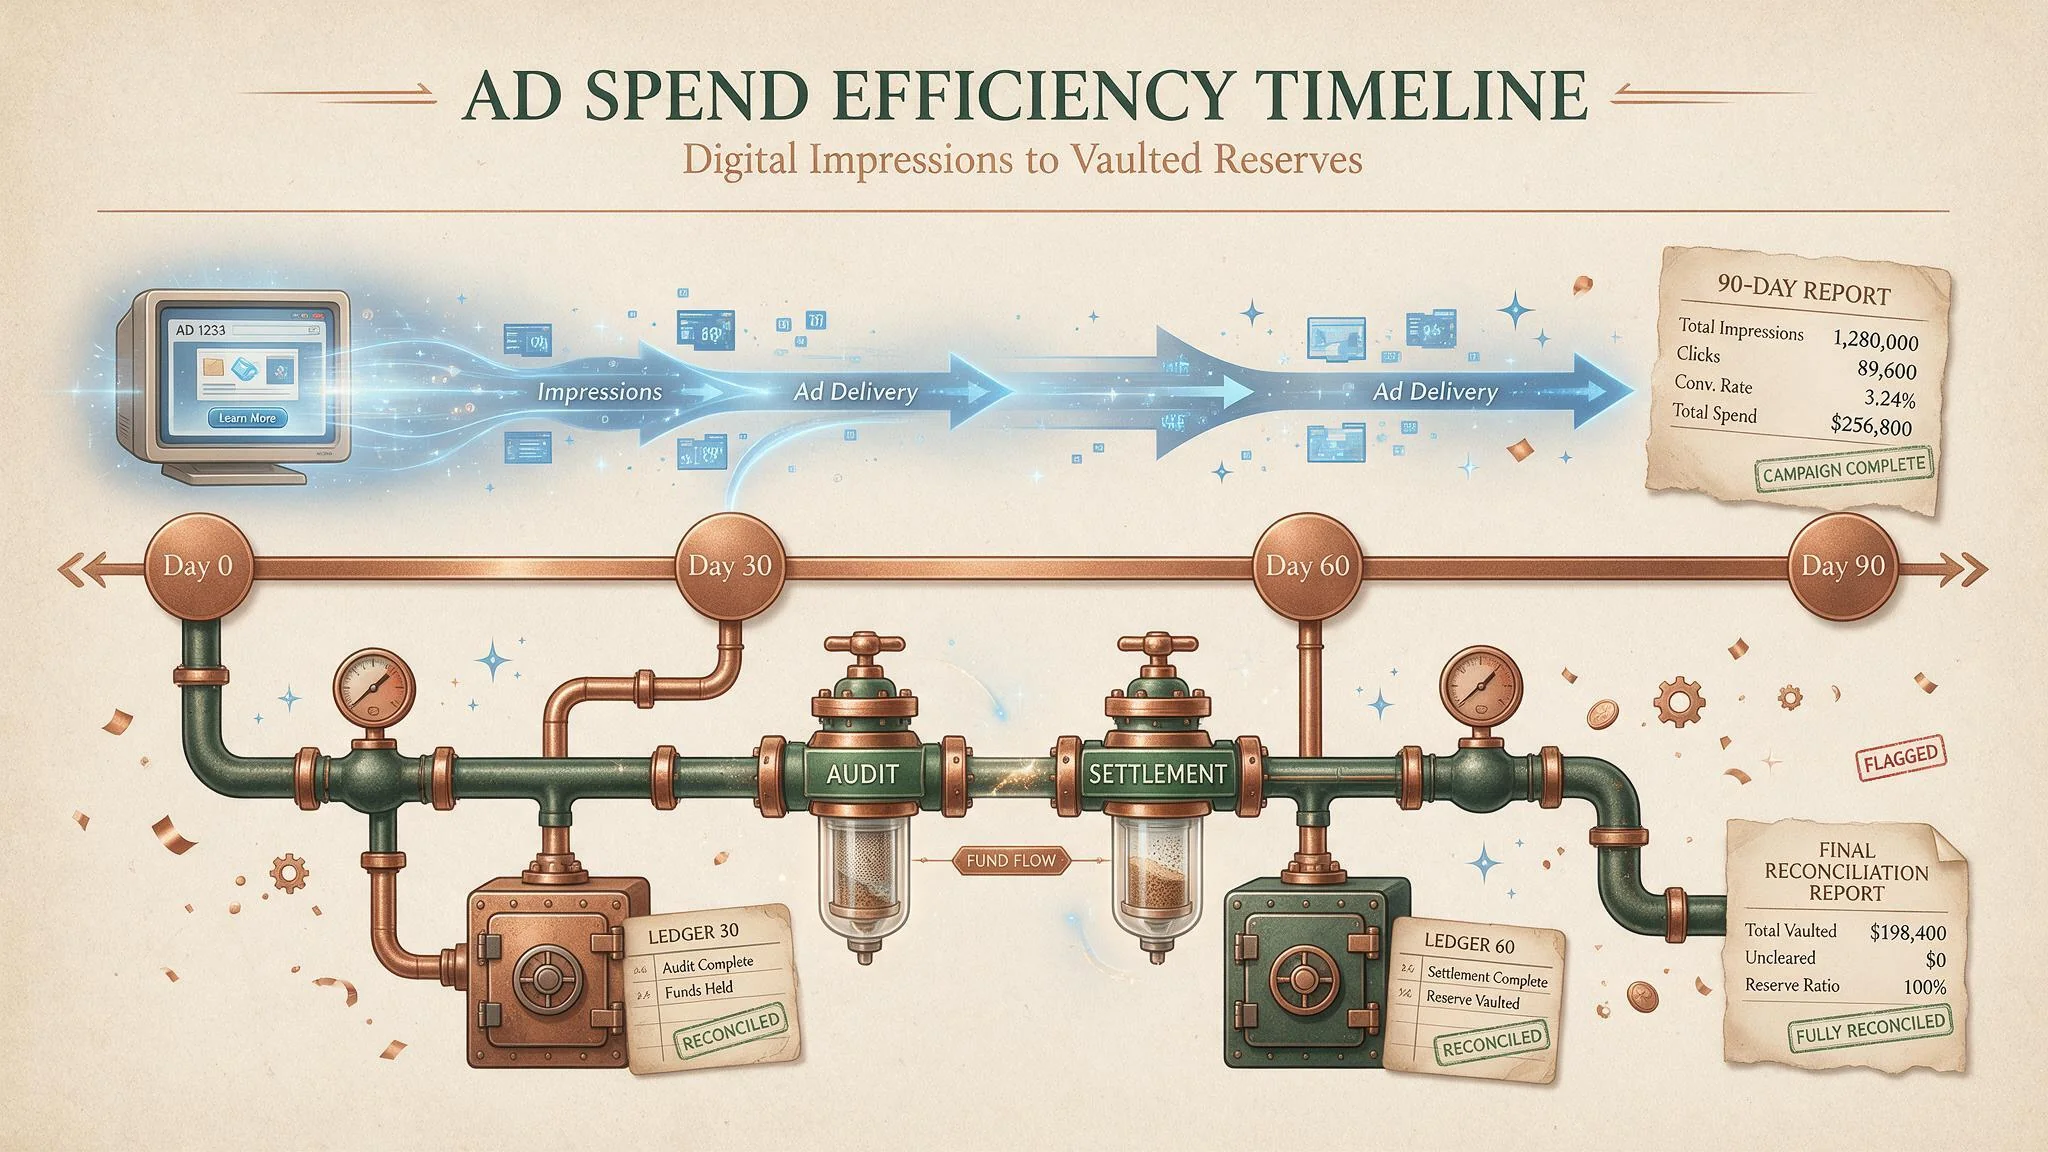
In programmatic advertising, real-time bidding protocols handle price discovery and ad delivery in milliseconds, while financial settlement relies on legacy monthly accounting cycles. Throughout a given calendar month, an SSP records billions of impression events across Prebid.js 11.x client wrappers, Prebid Server (Go/Java) clusters, Prebid Mobile SDK integrations, and Google Ad Manager (GAM) auctions. The settlement clock does not begin when an impression renders on the first day of the month; rather, it starts at 00:00:00 UTC on the first day of the following month, once the monthly billing ledger closes. Consequently, an impression served on May 1 under a Net-30 agreement actually takes 60 elapsed calendar days to convert into cash, whereas an impression served on May 1 under a Net-60 agreement takes 90 elapsed calendar days.
This multi-week delay originates at the very top of the programmatic supply chain. Major brand advertisers and their media holding agencies typically operate on 60-day to 90-day payment cycles with their contracted DSPs. When a tier-1 DSP executes media buys on behalf of an agency, the DSP generates a consolidated monthly invoice during the first week following the close of the activity month. Because the agency frequently takes 45 to 75 days to remit payment to the DSP, the DSP faces its own liquidity gap before it can settle accounts payable with downstream SSPs.
Different monetization channels manage this upstream float in distinct ways. Within the Google ecosystem, Google Ad Manager (GAM 360), AdX, and Open Bidding Direct Pay operate on a strict, reliable Net-21 to Net-30 remittance schedule, backed by Google's balance sheet and automated billing enforcement with participating buyers. Conversely, many independent SSPs structure their standard publisher contracts around Net-60 terms. That 60-day window gives the SSP enough time to reconcile impression logs with dozens of integrated DSPs, issue invoices by day 10 after month-end, collect DSP remittances around day 45 to day 55, and disburse net publisher payouts by day 60 without tapping into commercial credit lines.
When an SSP offers Net-30 terms across external DSP demand, the platform is effectively underwriting the float between its own payout date (day 30) and the date when slow-paying DSPs settle their balances (days 45 to 60). At Sky Boosts, we structure both Net-30 and Net-60 options across our publisher payment terms and monetization solutions, combining direct GAM MCM integrations and curated server-side demand so publishers can match payout velocity to their operational burn rate without sacrificing auction density.
Sequential Liability Clauses in IAB Standard Terms
The legal foundation governing why many programmatic platforms default to Net-60 or longer settlement windows lies in Section III(c) of the IAB/AAAA Standard Terms and Conditions for Internet Advertising (Version 3.0). This section establishes the doctrine of Sequential Liability. Under sequential liability, an agency or intermediary platform is solely liable to pay the downstream media seller if and only if the intermediary has received cleared funds from the upstream advertiser. If an advertiser declares bankruptcy or defaults on an invoice to its agency, or if an undercapitalized DSP fails to pay an SSP, sequential liability allows the intermediary to withhold the corresponding payout from the publisher unless the contract explicitly enforces joint and several liability.
For publishers evaluating SSP contracts, the difference between Net-30 and Net-60 is heavily tied to how the platform mitigates sequential liability risk. A platform operating on a pure pass-through sequential liability model cannot safely remit funds at day 30 if its upstream DSPs do not settle until day 55; doing so would expose the platform to unrecoverable clawbacks in the event of a buyer default. Institutional-grade SSPs protect publishers from this exposure by enforcing strict credit underwriting on connected DSPs, requiring letters of credit, and pruning high-risk buyers from the supply path before a single OpenRTB bid request is transmitted.
Clawbacks, Invalid Traffic (IVT) Deductions, and Invoice Reconciliation
The first 15 days immediately following the close of a calendar month (T+1 to T+15) are consumed by cross-platform log reconciliation and Invalid Traffic (IVT) auditing. Even when both the SSP and DSP utilize the OpenRTB 2.6 burl macro and VAST 4.3 impression pixels to standardize billable events, network packet loss, cellular connection drops on mobile apps, and CTV SSAI proxy timeouts create counting discrepancies of 1% to 3%. Simultaneously, MRC-accredited verification providers such as HUMAN and Pixalate execute post-bid batch analysis to identify Sophisticated Invalid Traffic (SIVT) patterns, such as data-center botnets, hidden ad containers, or spoofed app bundle IDs that evaded real-time pre-bid filters.
Publishers that monetize non-compliant traffic or permit high-risk ad categories often experience severe reconciliation delays and retroactive clawbacks during this window. By contrast, maintaining 100% Google-friendly, brand-safe inventory (strictly excluding alcohol, gambling, adult, tobacco, and unauthorized arbitrage) paired with continuous HUMAN and Pixalate pre-bid screening keeps post-month IVT deductions below 0.5%. When discrepancy and IVT variance remain negligible, invoice reconciliation between the SSP and DSP completes automatically by T+5, making reliable Net-30 disbursement financially sustainable.
AdOps data engineering teams can monitor this reconciliation spread internally by comparing raw auction wins against verified billable events and post-bid IVT flags in their data warehouse:
SELECT
    b.ssp_partner_id,
    b.payment_terms_days,
    COUNT(b.auction_id) AS raw_burl_fires,
    SUM(b.win_cpm_micros) / 1000000000.0 AS gross_estimated_rev_usd,
    SUM(CASE WHEN v.is_sivt = FALSE AND d.dsp_acknowledged = TRUE
             THEN b.win_cpm_micros ELSE 0 END) / 1000000000.0 AS net_billable_rev_usd,
    ROUND(
        (1.0 - (SUM(CASE WHEN v.is_sivt = FALSE AND d.dsp_acknowledged = TRUE
                         THEN b.win_cpm_micros ELSE 0 END)::NUMERIC
                / NULLIF(SUM(b.win_cpm_micros), 0))) * 100, 2
    ) AS discrepancy_and_ivt_deduction_pct
FROM prod_adops.openrtb_burl_events b
LEFT JOIN prod_adops.ivt_postbid_verifications v
    ON b.auction_id = v.auction_id
LEFT JOIN prod_adops.dsp_settlement_logs d
    ON b.auction_id = d.auction_id
WHERE b.event_date >= DATE_TRUNC('month', CURRENT_DATE - INTERVAL '1 month')
  AND b.event_date < DATE_TRUNC('month', CURRENT_DATE)
GROUP BY b.ssp_partner_id, b.payment_terms_days
ORDER BY net_billable_rev_usd DESC;
Calculating Effective Cost of Capital Between Net-30 and Net-60
To compare a Net-30 demand source against a Net-60 demand source objectively, publisher finance and yield teams must translate payment cycle duration into an annualized cost of capital. In corporate treasury management, a 30-day delay in cash collection carries an explicit financing cost equal to the publisher's Weighted Average Cost of Capital (WACC) or the annualized interest rate of its revolving credit or revenue-based factoring facility. For high-growth mobile app studios and web publishers utilizing invoice factoring or venture debt, short-term working capital typically carries an effective annual interest rate between 10% and 18%.
Moreover, when third-party factoring companies or SSPs charge an early-payment discount fee (for example, a 2% fee to accelerate a Net-60 invoice to Net-30), the annualized percentage rate (APR) is substantially higher than the nominal percentage suggests. Accelerating cash by 30 days for a 2% discount equates to borrowing money for twelve 30-day periods per year:
$$\text{Effective APR} = \left( \frac{\text{Discount Fee}}{1 - \text{Discount Fee}} \right) \times \left( \frac{365}{\text{Days Accelerated}} \right) = \left( \frac{0.02}{0.98} \right) \times \left( \frac{365}{30} \right) \approx 24.83%$$
Rather than ignoring this financing spread during real-time auctions, sophisticated publishers encode the time value of money directly into their header bidding wrapper. Using the bidCpmAdjustment hook in Prebid.js 11.x, AdOps engineers can normalize incoming gross or net bids to their Net Present Value (NPV) relative to a Net-30 baseline before those bids are passed to Google Publisher Tag (GPT) keys and compete against AdX in GAM.
// Prebid.js 11.x configuration: Time-Value-of-Money (TVM) Bid Adjustment
const PUBLISHER_ANNUAL_WACC = 0.14; // 14% annualized cost of working capital
const BASELINE_SETTLEMENT_DAYS = 30; // Net-30 benchmark (GAM AdX / Sky Boosts Net-30)

const BIDDER_SETTLEMENT_PROFILES = {
  skyboosts_net30: { revShareNet: 1.00, settlementDays: 30, ivtClawbackRate: 0.002 },
  skyboosts_net60: { revShareNet: 1.00, settlementDays: 60, ivtClawbackRate: 0.002 },
  tier1_ssp_alpha: { revShareNet: 0.85, settlementDays: 60, ivtClawbackRate: 0.015 },
  tier1_ssp_beta:  { revShareNet: 0.88, settlementDays: 90, ivtClawbackRate: 0.022 }
};

pbjs.que.push(function() {
  pbjs.setBidderConfig({
    bidders: Object.keys(BIDDER_SETTLEMENT_PROFILES),
    config: {
      bidCpmAdjustment: function(bidCpm, bidResponse) {
        const profile = BIDDER_SETTLEMENT_PROFILES[bidResponse.bidderCode];
        if (!profile) return bidCpm;

        // Step 1: Adjust for net rev-share and historical IVT/discrepancy deduction
        const expectedClearedCpm = bidCpm * profile.revShareNet * (1 - profile.ivtClawbackRate);

        // Step 2: Discount for extra days beyond the Net-30 baseline using daily WACC
        const extraFloatDays = Math.max(0, profile.settlementDays - BASELINE_SETTLEMENT_DAYS);
        const financingDiscountFactor = 1 / (1 + (PUBLISHER_ANNUAL_WACC * (extraFloatDays / 365)));

        return Number((expectedClearedCpm * financingDiscountFactor).toFixed(4));
      }
    }
  });
});
By applying this deterministic discount curve inside our unified monetization platform, a Net-60 bidder must clear a higher nominal CPM threshold (typically 1.15% to 1.50% higher at a 14% WACC, plus any historical discrepancy delta) to defeat a Net-30 bid in the unified first-price auction. If the Net-60 bidder cannot outbid the Net-30 baseline by at least the publisher's cost of capital, the auction awards the impression to the Net-30 demand source, accelerating cash flow without eroding risk-adjusted yield.
Structuring Hybrid Working Capital Reserves for User Acquisition (UA)
For mobile app developers scaling on iOS (via SKAdNetwork / AdAttributionKit) and Android, as well as web publishers running paid traffic acquisition campaigns, cash flow velocity directly governs company growth. Paid UA channels, including Google Ads and Apple Search Ads, typically bill credit lines weekly or enforce strict Net-30 settlement terms. When a publisher acquires a cohort of users on Day 1 that achieves a 115% Return on Ad Spend (ROAS) by Day 30, the unit economics are strongly positive. However, if the publisher's ad monetization stack is weighted entirely toward Net-60 SSPs, the cash generated by that cohort during Month 1 will not reach the publisher's bank account until Day 90. This 60-day cash conversion gap creates a working capital trough where the publisher runs out of liquid cash to fund Month 2 UA campaigns, precisely when cohort performance dictates scaling spend.
To eliminate this liquidity bottleneck without forfeiting the specialized demand density of Net-60 buyers, AdOps and finance teams should partition their programmatic stack into a two-tier hybrid liquidity architecture:
- The Base Liquidity Tier (Net-21 to Net-30): Allocate foundational inventory volume and high-velocity formats (such as mobile app banner/interstitial refreshes and high-viewability web display slots) to rapid-settlement pipes. This tier combines GAM AdX, Open Bidding Direct Pay, and Sky Boosts Net-30 demand. The predictable cash inflows from this tier should be sized to cover 100% of fixed monthly infrastructure obligations (cloud compute, SSAI transcoding, CDN bandwidth, payroll) plus the baseline revolving UA budget.
- The Yield Alpha Tier (Net-60): Layer specialized Net-60 SSP demand partners into Prebid Server, Prebid Mobile, and CTV VAST pod bidding specifically for high-CPM, lower-volume placements (such as rewarded video, CTV long-form mid-rolls, and high-impact native units). By enforcing the WACC-adjusted
bidCpmAdjustmentor raising price floors on Net-60 line items in GAM by 2% to 4%, Net-60 partners only win impressions when they deliver genuine price superiority that compensates for the extra 30 days of float.
Implementing this hybrid structure transforms programmatic yield management from a static reporting exercise into an active treasury control system. Start by auditing your current DSO weighted by partner revenue share, quantifying historical IVT and discrepancy deductions per SSP, and applying time-value-of-money adjustments in your Prebid configuration. If your organization is looking to compress its cash conversion cycle through clean, brand-safe demand on reliable Net-30 or Net-60 schedules, contact our publisher team to architect a settlement and bidding strategy tailored to your inventory.